Fireside Chat: Canada's Challengers Weigh Clarity, Competition and Becoming a Bank
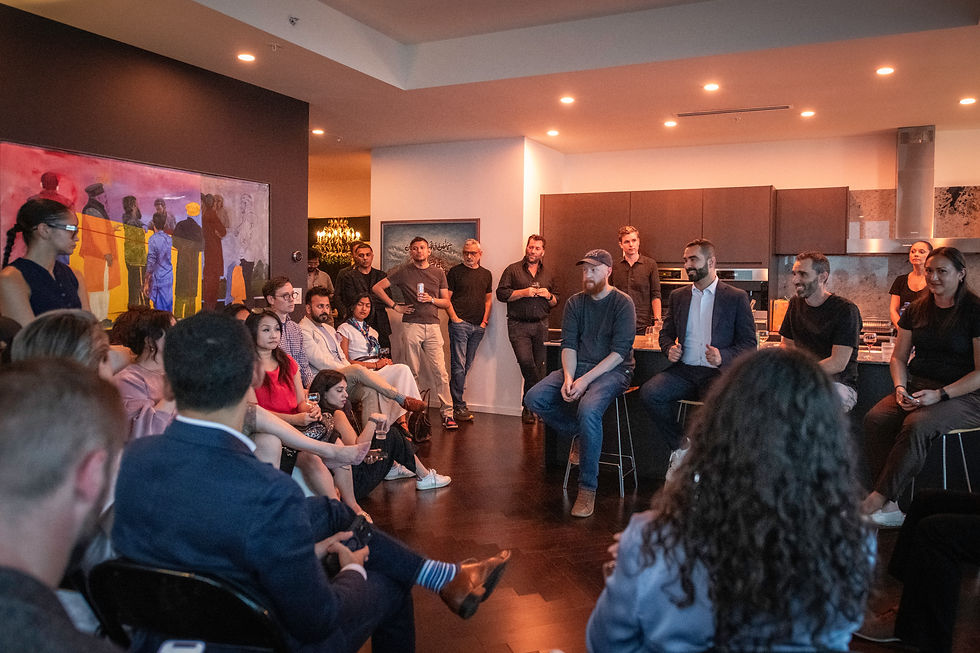
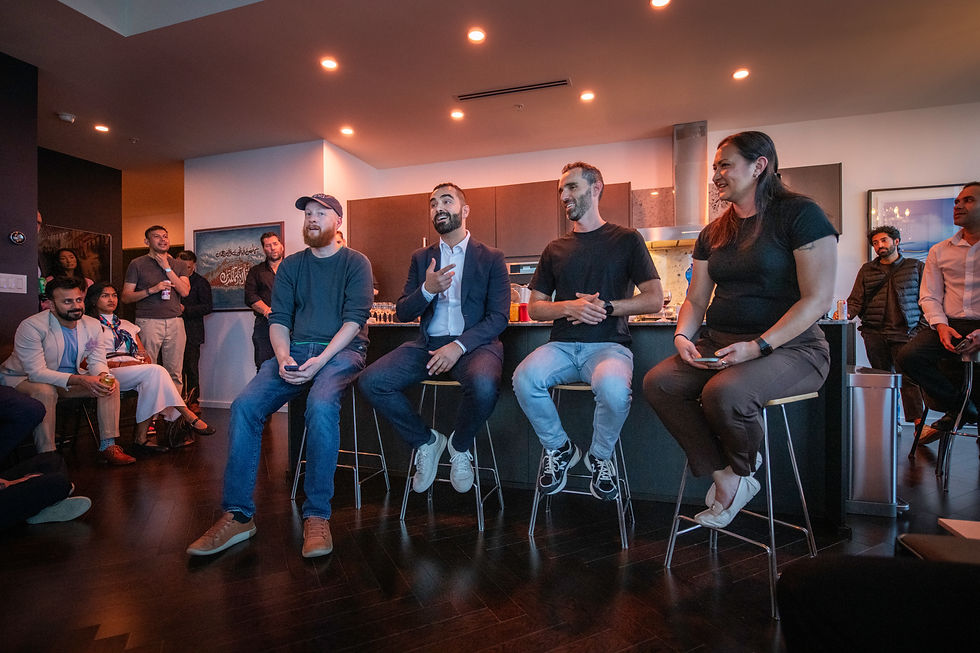
On September 16, Sixty floors up in downtown Toronto set the tone for an engaging fireside chat with CPPO board member David Merriby, CEO of the future KOHO Bank, and Eric Richmond, Country Director and CEO of Coinbase Canada. Alex Johnson, founder of Fintech Takes, and Kiah Lau Haslett, creator of Fintech Takes Banking, moderated the discussion as part of their tour of the Canadian banking and fintech ecosystem.
Innovation in banking and fintech often starts with honest, open conversation about how everyone can work together, whether that means banks and fintechs finding common ground or partners comparing notes across borders. About 45 banking, payments and fintech leaders came together to have that conversation.
The fireside chat compared how Canada and the US are modernizing banking and payments as new regulations take shape and the way money moves keeps changing.
The group worked through several questions:
Who should be allowed to move money?
Who can hold it?
What protections should apply?
How much access should new entrants have to the core banking system?
The discussion opened with digital assets. Canada was among the first countries to approve regulated crypto products and dealer frameworks, and much of that early progress followed court decisions and industry failures.
The panel compared that history with the current US approach, where regulators are continuing their rulemaking while federal legislation remains unsettled, and discussed the value of clear, proactive rules that give Canadian entrepreneurs a defined path to build on. Consumer interest in Canada has grown considerably in recent years, and the conversation touched on crypto's dual role as an investment and as infrastructure for moving money, along with the growing number of financial advisors discussing it with clients.
The focus then turned to banking. Canada's market is highly concentrated among a few large institutions, a structure the panel connected to both the system's stability and to longstanding concerns about fees and payment options.
Competition is now coming from fintechs, digital banks and US institutions expanding their Canadian presence. Panelists also discussed how federal regulators are rethinking their approach. With more financial activity taking place outside the federal framework, regulators have moved to shorten approval timelines for new banks and have signaled more openness to supporting finanical innovation.
The risk used to be concentration among the big banks. Now it's the growing number of fintechs operating outside the federal framework, so the government is encouraging them to come inside it and making that path easier. Regulators are now willing to license newer players as long as their compliance, risk and governance structures are sound, the group noted.
For a fintech, becoming a bank brings customer trust, deposit insurance and the ability to use customer deposits to fund lending instead of holding them in segregated accounts. The panel also connected the move to a broader goal of competing with established banks on fees. Those benefits come with new obligations, including an independent board, multiple lines of risk and compliance oversight and the staff to support them, and the discussion weighed those added costs against the long-term economics of holding a charter.
For KOHO, the move to become a bank ties back to its founding goal of challenging the big banks on fees and offering banking in a different way. David pointed out that fintechs and banks already share a lot of the same obligations, since privacy and anti-money-laundering rules apply to both. The real difference he described is cultural. Becoming a bank brings bank-level governance, and the challenge is keeping a fintech's speed and decision-making inside that structure.

The conversation closed on how a fintech keeps its culture once it becomes a bank. Topics included separating regulated banking products from more flexible offerings in a distinct entity, using AI and outsourcing to reduce compliance workloads, and communicating with the board frequently enough to keep decisions moving. Panelists also noted that privacy, anti-money-laundering and many consumer protection rules already apply to fintechs, so much of the change comes from governance and process.
The evening ended where it began, with baking and fintech leaders comparing notes on how Canada's financial system is evolving and where new entrants fit within it.


Comments